Global Markets: AI Concerns Drive Rotation Away from US Growth
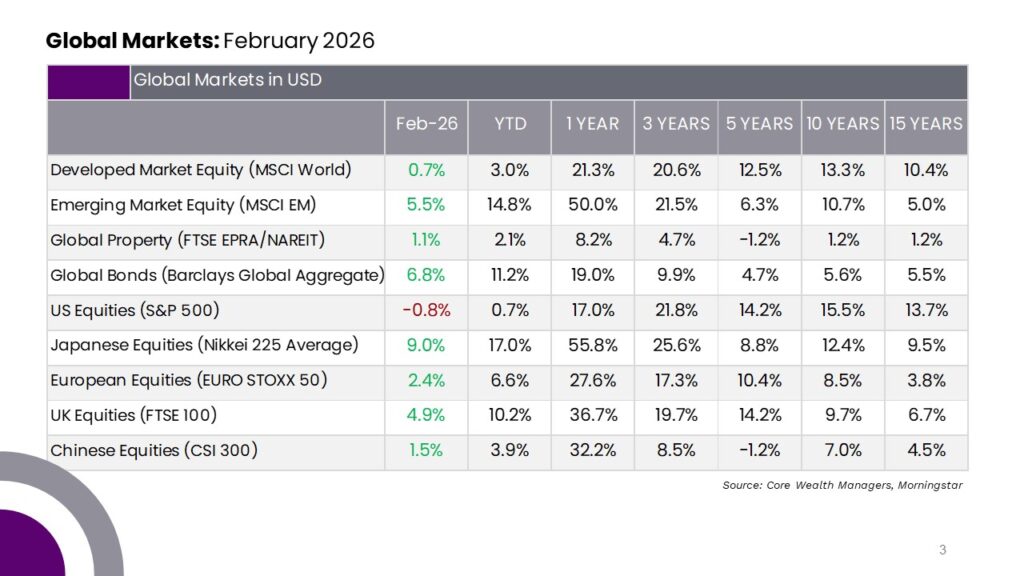
Global equity markets delivered modest gains in February, with the MSCI World Index rising +0.7% MoM, despite a –0.8% MoM decline in the S&P 500. A key theme was the continued rotation away from US growth stocks toward global value shares. Value outperformed meaningfully, advancing +2.9% MoM, while the Russell 1000 Growth Index declined –3.4% MoM.
The “Magnificent Seven” fell –7.3% MoM as investors reassessed the scale of AI-related capital expenditure and the potential for margin pressure from rapid generative AI adoption. Notably, even companies delivering solid earnings — including IBM (–21% MoM), Booking.com (–15% MoM), and S&P Global (–16% MoM) — experienced sharp share price declines. This reflects increasingly cautious sentiment toward technology and AI-exposed sectors, alongside a broadening of market leadership beyond US mega-cap growth stocks.
Emerging Markets Extend Outperformance
Emerging market (EM) equities continued to outperform developed markets in February, extending their year-to-date lead into double digits. The MSCI Emerging Markets Index rose +5.5% MoM and +14.8% YTD, supported by strong performance from commodity-producing economies such as Brazil (+4.1% MoM) and South Africa (+7.0% MoM).
This strength came despite notable weakness in Chinese technology stocks. Tencent (-15% MoM), Alibaba (-16% MoM), Meituan (-17% MoM), and Baidu (-19% MoM) all declined during the month. Baidu also reported a third consecutive quarterly revenue decline, while intensifying competition among Chinese online retailers, alongside speculation around higher VAT on e-commerce, weighed on sentiment.
Meanwhile, rising risk aversion saw the US 10-year government bond yield fall by 0.3% to 3.9% p.a., its first close below 4% in over two years. The US dollar strengthened modestly against most developed market currencies but weakened against several EM currencies.
South Africa: Strong Equity Performance and Improving Fiscal Outlook
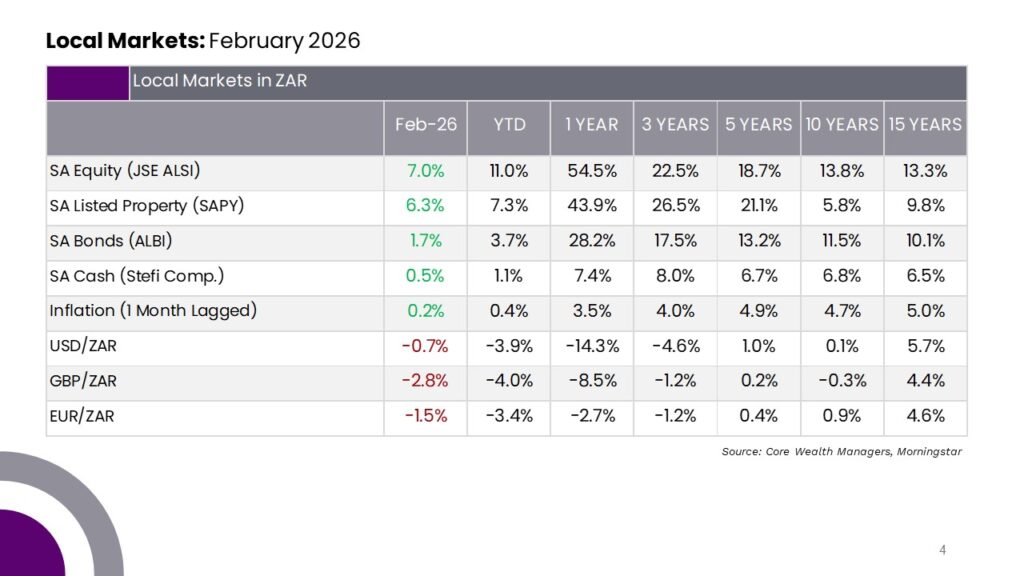
South African equities were again among the strongest global performers in February. The FTSE/JSE Capped All Share Index advanced +7.0% MoM, taking year-to-date gains to +11%. Over the past year, the JSE has delivered an exceptional +80.3% return in US dollar terms, supported by both strong equity performance and a firmer rand.
Performance reflected a combination of commodity strength and improving sentiment toward domestically focused sectors, particularly financials. Banks and insurers delivered solid gains, with Nedbank (+19% MoM) and Discovery (+11% MoM) standing out following positive operational updates.
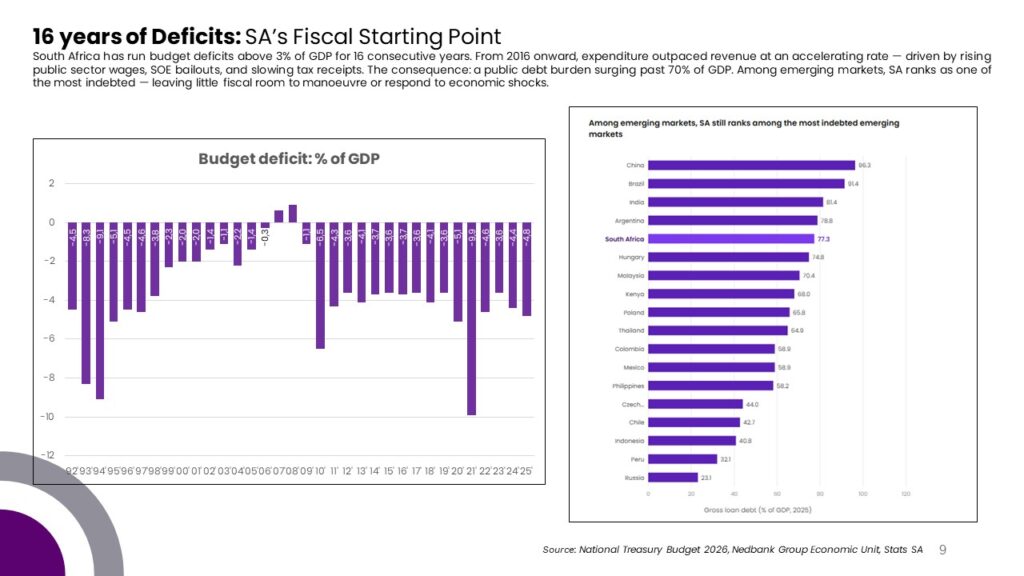
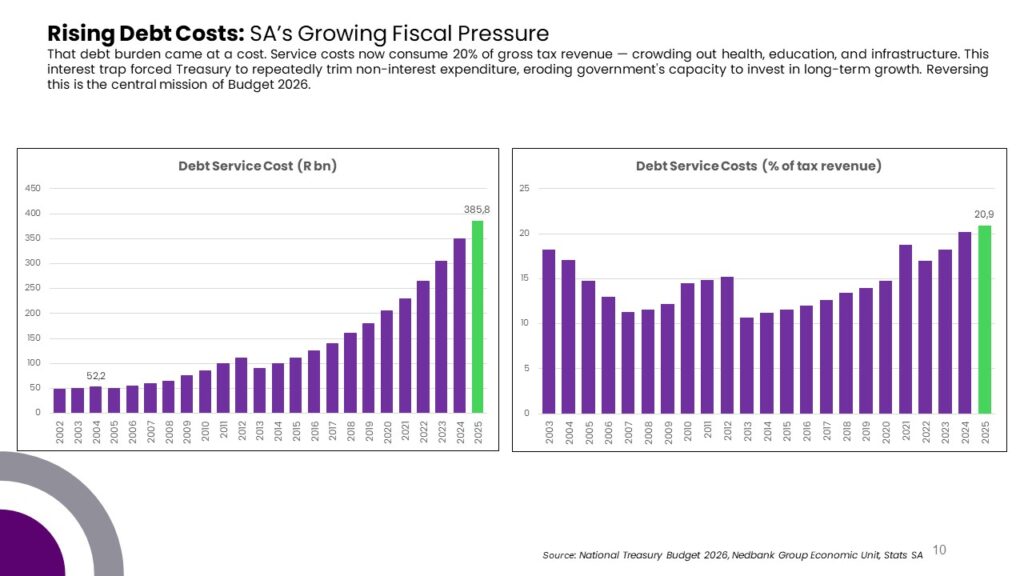
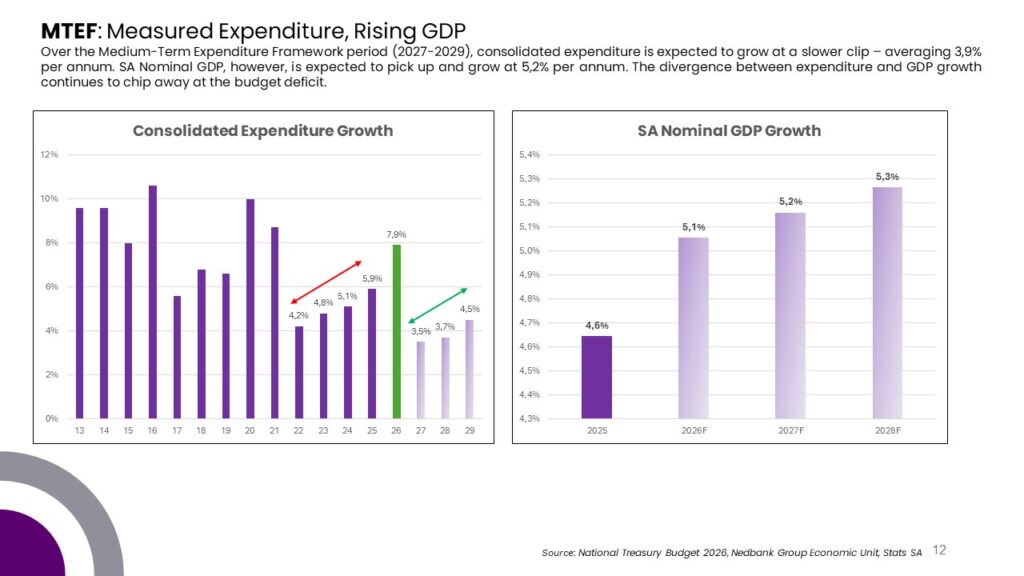
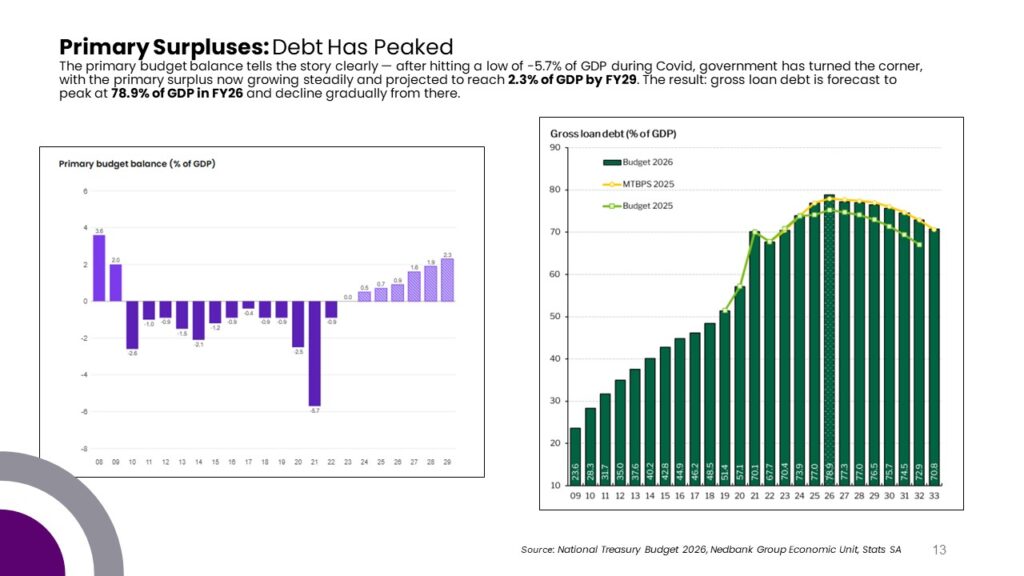
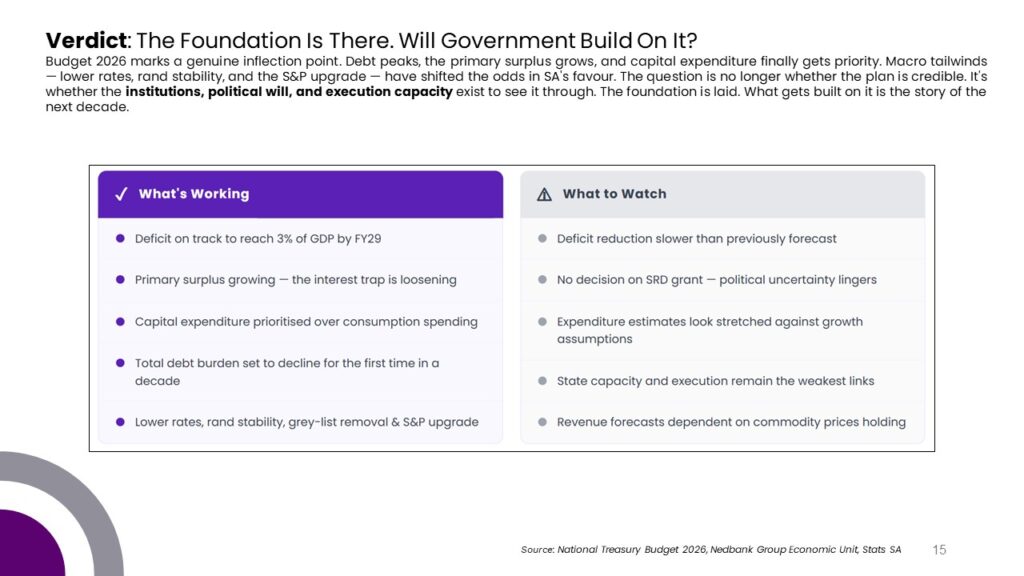
On the macro front, the national budget was broadly well received, reinforcing the fiscal consolidation narrative as the deficit narrows and government borrowing costs remain contained near multi-year lows of approximately 8%.